When the Money Stops Flowing: What a London Penthouse and a Vancouver Developer Have in Common
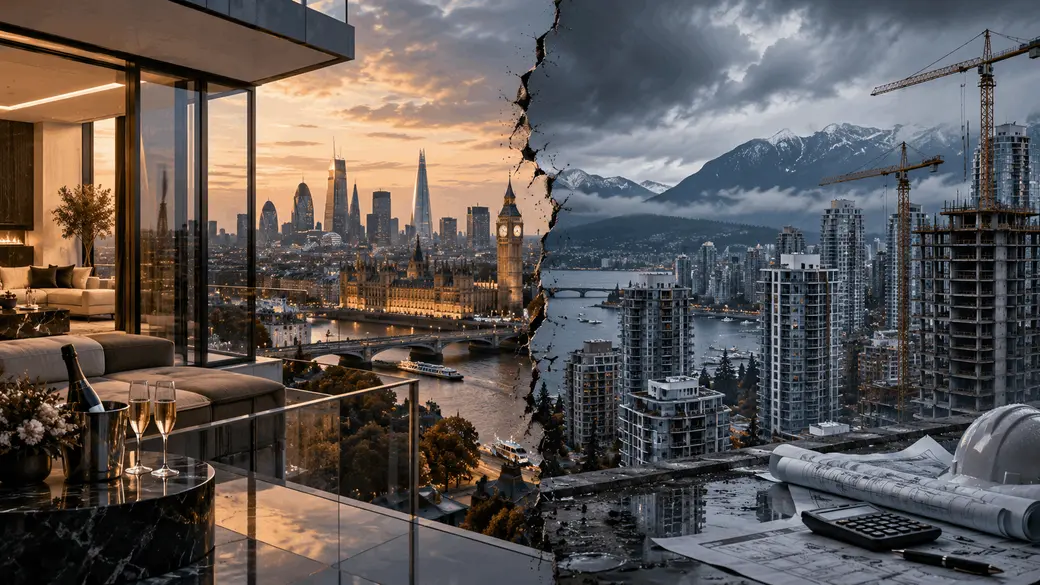
When the Money Stops Flowing: What a London Penthouse and a Vancouver Developer Have in Common
This piece started as routine coverage of a London property story reported the week of September 7, 2026 — the kind of case study we normally use to explain how real estate financing works. Looking into it raised a broader question worth answering properly: when the structure behind a high-value property or development starts to come apart, how hard is it — for lenders, courts, and the public — to work out who actually owns it, who financed it, and who's on the hook? That question led us from London to a Vancouver case much closer to home.
A Kensington Penthouse, Frozen in Receivership
Two penthouses at 3a Palace Green in Kensington, overlooking Kensington Gardens, were purchased for a combined £35.75 million in 2014 and 2016. Both are registered to Ali Ansari, an Iranian banker the US Treasury designated in July 2026 as a key financial facilitator for the Iranian regime. Both apartments are now in receivership after Ansari defaulted on the mortgages — meaning the lenders appointed an independent receiver to sell the properties and recover what's owed. The larger unit is listed at just under £12 million, roughly £7 million under its 2016 purchase price.
Ansari has publicly denied any financial relationship with Iran's Islamic Revolutionary Guard Corps or its Supreme Leader, and has said he intends to pursue legal action against the UK government over the sanctions. None of the allegations against him have been tested in a criminal court.
One detail in the sales material is what actually connects this story to Vancouver: because the properties are in receivership, the listing agents don't have access to all the usual information a buyer would expect, and purchasers are advised to do their own investigating. That's a genuinely unusual situation for a London property — and it's a direct result of financial distress exposing gaps in what anyone can actually confirm about a property's history.
Why Large Real Estate Deals Are Rarely Simple
Major developments routinely require tens or hundreds of millions of dollars, so it's normal — not suspicious — to see multiple companies, investors, and lenders behind a single project. A developer typically sets up a separate company for each property, brings in equity partners to share the capital, and takes out a first mortgage and often a second. Guarantors personally back the debt. None of that is unusual, and none of it is evidence of anything improper.
Complexity does not equal corruption. Multiple corporations, multiple lenders, and layered financing are how large real estate gets built. The interesting part — and the part worth understanding as a buyer, seller, or investor — is what happens to that structure once something goes wrong.
Vancouver: Shawn Oaks and the Layers Underneath
Vancouver developer Helen Chan Sun, sole shareholder and CEO of Landmark Premiere Properties Ltd., is a useful real-world example of exactly this. Landmark's Shawn Oaks site — a 3.2-acre, 72-unit townhouse property near Oakridge, where Landmark had proposed two residential towers — was placed into receivership in February 2025.
The financing behind it was entirely ordinary until it wasn't: a first mortgage of $67.7 million from Trez Capital (advanced in 2019), and a second mortgage of $25 million from Peterson Investment Group (advanced in 2021). When the first mortgage matured in September 2024 and went unpaid, the combined debt reached roughly $99 million, and both lenders moved to recover it through the courts.
In its court filing, Peterson stated Landmark "failed to properly disclose the majority investor" behind the companies that owned the Shawn Oaks site. Landmark's own explanation, given publicly, is that it held a 30% stake while two equity partners holding the remaining 70% stopped making shareholder payments starting in 2018 and 2019, leaving Landmark to carry the project's debt alone. Both statements are on the public record. Whether they describe the same investors — or two different problems — has not been publicly resolved, and the identity of that ownership has not been disclosed anywhere in the public reporting we've reviewed.
That's the plainest illustration of the whole article's premise: a project can look like a conventional development from the outside, and once it lands in receivership, a basic question — who actually held the equity? — turns out not to have a public answer.
The Personal Side: A Separate, Older Dispute
Separately from Shawn Oaks, Sun personally guaranteed a $4.5-million mortgage in 2018, tied to an unrelated, failed Burnaby project. When that debt went unpaid, a BC Supreme Court registrar reviewed her finances in December 2024 and found her "cash poor" claim didn't hold up — citing documented luxury spending inconsistent with the $60,000–$70,000 annual income she claimed, and ordering her to pay $300,000 a month until the debt was cleared.
She didn't fully comply. That led to a suspended 40-day contempt sentence, activated in May 2026, and — while she was still in custody — a second judge declared her personally bankrupt in June 2026.
None of this is a fraud conviction. Civil contempt is a finding that someone failed to comply with a court order — in this case, a financial disclosure and payment order. Bankruptcy and receivership are insolvency processes, not findings of criminal wrongdoing. No fraud charge appears anywhere in the public record we reviewed.
Foster Martin: What This Actually Means for a Buyer
This is where the story becomes concrete for an ordinary reader, because Landmark's Foster Martin project in White Rock is a real presale development with real buyers — and it's important to be precise about which part of it is actually affected.
Foster Martin is three towers. Two of them — The Martin (121 units) and The Foster (113 units) — are complete, occupied, and trading normally on resale. The third, Landmark Tower (128 units, 93 of them pre-sold, representing roughly $131 million in presale value), was still finishing construction as of mid-2026. It's this third tower — not the whole project — where the consumer-protection question actually lives.
When Sun's personal bankruptcy was being decided in June 2026, Landmark itself argued that the bankruptcy could trigger buyers' rights to rescind their contracts under BC's Real Estate Development Marketing Act — legislation that requires developers to keep purchasers informed of material changes affecting a project. The presiding judge, Justice Gordon Weatherill, assessed that risk as low and granted the bankruptcy order anyway.
At that same hearing, Weatherill considered an order to protect the assets of the companies developing Foster Martin — until he asked a simple question: given that Sun was no longer a director of Landmark Premiere, was she still even a shareholder of those companies? Her lawyer asked for time to find out rather than answer directly. The judge gave him until after lunch. Reporting doesn't show a clean answer was ever produced on the record that day.
That's the clearest version of this entire story in one moment: a sitting judge, in open court, asking who currently owns an active development company — and not getting an immediate answer. It doesn't mean anything was hidden improperly. It means that once a structure comes under real pressure, even the most basic ownership question can become surprisingly hard to answer quickly.
London and Vancouver, Side by Side
These two cases have nothing to do with each other. A sanctioned Iranian banker's London penthouses and a Vancouver developer's insolvency share no connection beyond the structural pattern both illustrate. But that pattern is the real story: complex, layered ownership is how large real estate gets financed — normal, legal, and usually invisible, because it never has to be untangled while everything is going well.
It only becomes visible under stress. A mortgage default. A receivership. A bankruptcy filing. That's when a lender, a court, a buyer, or a reporter has to ask the same basic questions this article has walked through: who owns this, who financed it, who's guaranteed the debt, and who gets paid first. Sometimes those answers come quickly. Sometimes — as with Shawn Oaks' still-unidentified majority investor, or a judge in a Vancouver courtroom waiting on a lunch-break answer — they don't.
Frequently Asked Questions
Are the London and Vancouver cases connected?
No. There is no evidence the parties know each other or have any relationship. The connection in this article is structural — both cases illustrate what happens to complex ownership and financing when a property or project runs into serious financial trouble.
Does any of this mean fraud occurred?
No criminal fraud conviction is being alleged in this article. Ansari has been subject to government sanctions and disputes the allegations underlying them. Sun's matters discussed here involve civil contempt, receivership and personal bankruptcy. Those are distinct legal processes and should not be treated as criminal fraud findings.
Should I be worried about buying a presale unit anywhere?
Not because of this article specifically. But it's a good reminder to ask direct questions before committing to a presale: who is the actual developer entity, who is financing the project, and where do your deposits sit. Most presales complete without incident — but complexity is easier to ask about before you sign than to untangle afterward.
Sources & References
- [1] London penthouses, purchase price, receivership, and sales-material disclosure language. The Sunday Times, as reported by Gulf News and VIN News. gulfnews.com / vinnews.com
- [2] US Treasury designation of Ali Ansari, July 2026, and Ansari's public denial and stated intention to pursue legal action. Kurdistan24. kurdistan24.net
- [3] Shawn Oaks mortgage amounts, receivership filing, and Peterson's undisclosed-majority-investor statement. STOREYS. storeys.com
- [4] Landmark's 30%/70% ownership explanation and its statement on the isolated nature of the Shawn Oaks insolvency. STOREYS. storeys.com
- [5] GC Capital Inc. v. 1161359 B.C. Ltd., 2024 BCSC 2378 (Registrar Gaily, December 30, 2024) — credibility findings, luxury spending, and the $300,000/month payment order. British Columbia Supreme Court. bccourts.ca
- [6] Sun's contempt sentence, jailing in May 2026, and personal bankruptcy in June 2026, including the Foster Martin shareholder exchange between Justice Weatherill and counsel. CBC News. cbc.ca / cbc.ca
- [7] Foster Martin project details, tower breakdown, presale figures, and REDMA rescission-risk argument. CBC News. cbc.ca
Debbie Evans, REALTOR®
eXp Realty | West Vancouver, North Shore & Sea-to-Sky Markets
If you're evaluating a presale purchase or want help understanding what a specific project's ownership and financing structure actually looks like, that's a conversation worth having before you sign — not after.
westvanliving.ca · debbie.evans@exprealty.com · +1 (778) 875-4934
This article is provided for general informational and educational purposes only and does not constitute legal, financial, investment or real estate advice.
It is based on publicly available court decisions, court and insolvency filings, government sanctions records, media reporting and other cited sources available at the time of publication. Court proceedings, receiverships, bankruptcies and related matters may continue to develop after publication.
Nothing in this article should be interpreted as an allegation of criminal conduct, fraud, money laundering or other criminal wrongdoing unless expressly identified as a finding or charge by the appropriate court, regulator or law-enforcement authority.
Government sanctions, civil contempt, receivership, foreclosure and bankruptcy are distinct legal processes and should not be treated as criminal convictions. Where allegations, submissions or disputed claims are discussed, they are attributed to the person, party, government agency or source that made them and should not be understood as judicial findings unless expressly stated.
Multiple corporations, investors, lenders, mortgages, project-specific entities and beneficial ownership structures are common in large real estate developments and do not, by themselves, indicate improper conduct.
The London and Vancouver matters discussed in this article are separate and unrelated. They are compared solely to illustrate broader issues involving real estate ownership, financing, disclosure and financial distress.
Readers considering a specific property, development or investment should conduct their own due diligence and obtain independent legal and financial advice appropriate to their circumstances.
Categories
- All Blogs (97)
- aboriginal title ruling (2)
- bc housing market (23)
- bc real estate (55)
- Bill C-15 (1)
- build canada homes (8)
- Buyers Guide (4)
- canada strong fund (3)
- Canada-U.S. Trade (2)
- canadian real estate (15)
- Climate Change (2)
- Design & Build (4)
- Dundarave West Vancouver (1)
- Equity Growth (1)
- freehold (1)
- Home Buying Tips (1)
- housing policy (1)
- land claims (2)
- Land Claims / BC Real Estate (1)
- leasehold (1)
- local news (1)
- Lower Lonsdale (2)
- Market & Policy Analysis (1)
- Market Commentary (6)
- market insights (23)
- Multigenerational Living (2)
- North Vancouver Real Estate (19)
- open house (1)
- Open House Security (1)
- presale (1)
- real estate insights (7)
- Real Estate Market & Housing (2)
- Squamish Market Update (7)
- squamish real estate (8)
- squamish update (3)
- Vancouver Real Estate (17)
- West Vancouver Living (15)
- West Vancouver Real Estate (26)
- Whistler Market Update (4)
Recent Posts
Have a Question? Let’s Talk. I’m Here to Help.
North Shore & Vancouver Realtor License ID: 175378
+1(778) 875-4934 | debbie.evans@exprealty.com